
Corporate Gifting and the IRS $25 Rule, Explained
Pacific Gift Box Co.
·Published July 24, 2026 · Updated October 24, 2026
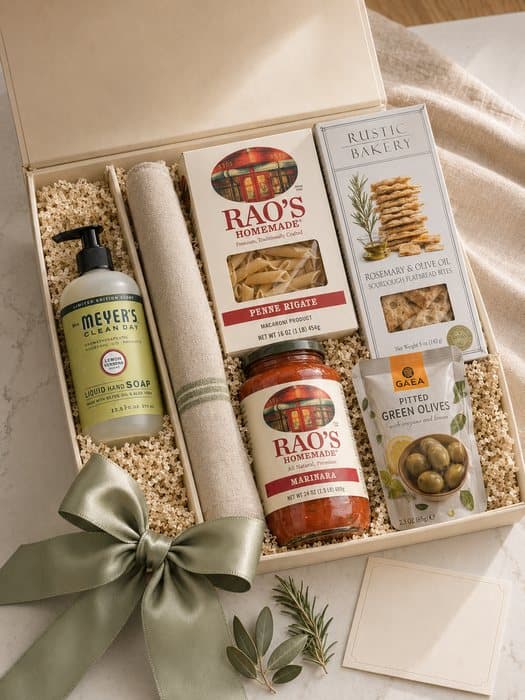
If you've ever written a check for client gifts and wondered what you could actually write off, you're not alone. The corporate gift tax deduction is one of the most misunderstood line items in a small business budget — and one of the easiest to get wrong. The IRS has a hard cap that most business owners don't know about until tax season, and the rules around what counts, what doesn't, and how to document it correctly can save you real money if you understand them before you buy.
A corporate gift tax deduction is a business expense deduction permitted by the IRS for gifts given to clients, customers, or business associates — capped at $25 per recipient, per tax year, under IRC Section 274(b), regardless of what you actually spend. This guide breaks it down plainly: what the deduction is, how it works in practice, and how to build a gifting budget that is both tax-smart and actually meaningful to the people receiving the gift.
2026 order-by dates
| Order type | Thanksgiving | Christmas |
|---|---|---|
| Non-branded, shipped nationwide | Tue, Nov 10 | Mon, Dec 14 |
| Non-branded, SoCal, 50+ boxes | Tue, Nov 17 | Fri, Dec 18 |
| Custom-branded (logo, ribbon, inserts) | Fri, Oct 23 | Fri, Nov 20 |
Boxes run $59–$179, shipping included. Orders start at 12 boxes; custom and logo-branded boxes start at 100. See the Holiday Collection and get a quote.
The IRS $25 Rule: What It Actually Says
The Definition You Can Take to Your Accountant
The $25 cap comes from IRC Section 274(b), and it hasn't changed since 1962. That's not a typo. The limit was set over sixty years ago and has never been adjusted for inflation. The IRS has not signaled any near-term intent to update it, so plan accordingly.
Here's what that means practically: if you spend $80 on a gift box for a client, you can deduct $25 of it. The remaining $55 comes out of your pocket, after tax. That doesn't make the gift a bad idea — it just means the corporate gift tax deduction is a bonus, not the reason to give.
What Counts Toward the $25 Cap (and What Doesn't)
The IRS draws a few distinctions worth knowing:
- Only incidental costs sit outside the cap. Engraving, gift wrap and postage are not counted toward the $25 per-person limit, provided they add no substantial value of their own. The box and what is in it count toward the $25 figure, however carefully it is packed.
- Items with your logo may qualify as advertising. Branded merchandise given broadly — a pen with your company name handed out at a trade show — may be deductible as an advertising expense rather than a gift, bypassing the $25 cap entirely. The IRS generally allows this for items costing $4 or less with your business name clearly on them. A curated gift box with a personal product selection is not this.
- Both spouses count as one recipient. If you give a gift to a client and also send something to their spouse, the IRS treats them as a single recipient. Your combined deduction is still $25, not $50.
- Cash and gift cards are treated differently. Cash and cash-equivalent gifts to employees are generally treated as wages, not gifts, and are fully taxable to the recipient regardless of amount. This is a separate set of rules from client gifts.
The IRS's own example in Publication 463 (Travel, Gift, and Car Expenses) draws the boundary: an ornamental basket used to present a gift of fruit is not treated as incidental if the value of the basket is substantial relative to the fruit. Applied to a gift box, tissue and ribbon are gift wrap and clear that bar; a presentation box whose cost rivals the product inside it is the case that might not.
Employee Gifts vs. Client Gifts: Different Rules Apply
If you're gifting employees rather than clients, the rules shift. Employee gifts under a de minimis threshold — generally low-cost, infrequent items like holiday food or branded notebooks — may be excludable from their income under IRC Section 132(e). Anything more substantial is typically treated as compensation. Talk to your CPA about your specific situation — this article is educational, not tax advice.
How to Think About Gifting Budget When the Deduction Is Capped at $25
The Real ROI Isn't the Write-Off
Here's the honest take most tax articles skip: the corporate gift tax deduction is almost irrelevant to whether gifting makes business sense. If you're in the 25% tax bracket, that $25 deduction saves you $6.25. The actual value of a well-chosen gift — a client who renews, a referral you didn't have to chase, an employee who stays through Q1 — is worth substantially more than that.
That's the part no tax code can capture. A $59 box packed with intention lands differently than a $179 swag kit pulled from a catalog. That distinction is also exactly why the team at Pacific Gift Box Co. hand-packs every box — because thoughtfulness is the point, and no algorithm replicates it. Orders start at 12 boxes, with no contracts and no junk filler chosen to hit a price point.
A Realistic Scenario: The Office Manager at a Referral-Driven Firm
Picture this: you manage operations for a 12-person financial advisory firm. Every December, your principal wants to send holiday gifts to the firm's 25 top referring CPAs and attorneys. Last year, someone ordered branded tote bags from a promotional catalog. Half came back to the office in a pile. This year, you have a $1,500 budget and a goal of actually being remembered in January.
Using curated boxes from Pacific Gift Box Co. — hand-packed, no catalog selection, orders starting at 12 boxes — you send 25 boxes at $59 each. Your total spend is $1,475. Your corporate gift tax deduction is $25 × 25 recipients = $625 deductible. At a 24% effective federal rate, that's roughly $150 back at tax time. Not transformative — but your documentation is clean and your recipients got something they actually kept. That's the real math.
A Practical Budget Framework for Business Gifting
Use this comparison table to match your gifting tier to your business relationship and deduction reality:
| Gift Occasion | Typical Spend Range | IRS-Deductible Portion | What Actually Works |
|---|---|---|---|
| Holiday client thank-you | $59–$99 | $25 | Curated food, artisan goods, handwritten note |
| New employee welcome | $72–$101 (shipping quoted separately) | De minimis rules apply; consult CPA | Practical + personal items; skip logo mugs |
| Referral thank-you | $89–$179 | $25 (client gift rules apply) | Premium tier, meaningful, keeps you top of mind |
| Closing/deal milestone | $129–$179 | $25 | Elevated box, personal curation, no fluff |
| Branded swag drop | Varies | May be advertising expense instead | Usually skipped or ends up in a junk drawer |
Documentation: The Part Most Business Owners Skip
What the IRS Expects You to Keep
Even a modest corporate gift tax deduction requires documentation to hold up under scrutiny. The IRS expects you to record:
- The cost of the gift
- The date it was given
- A description of the gift
- The name and business relationship of the recipient
- The business purpose for the gift
A folder in your accounting software with receipts and a one-line note per recipient is usually sufficient. If you're sending 30 client gifts in December, a simple spreadsheet with those five columns covers it. The documentation habit takes five minutes and protects the deduction entirely.
How to Build a Documentation System That Takes Five Minutes a Year
The simplest approach: create a single spreadsheet in December with columns for recipient name, business relationship, gift description, date sent, and amount spent. Attach your order confirmation or receipt as a PDF in the same folder. Store it alongside your other business expense records and hand the folder to your bookkeeper or CPA in January. That's the entire system.
A Documentation Scenario That Makes This Concrete
Say you're an office manager at a mid-size real estate firm. You send 20 holiday gift boxes to your top referring agents — each box runs $69. Your total spend is $1,380. Your deductible amount is $25 × 20 = $500. At a 25% effective tax rate, that's $125 back. Not the reason you sent the boxes, but a real number, and fully defensible with a spreadsheet and your receipts.
The same logic applies when comparing onboarding gift boxes to company swag — the retention value of a well-chosen welcome gift to a new hire typically dwarfs whatever the tax treatment is. And if you're thinking about gifts for remote team members specifically, timing, shipping, and what actually travels well are a separate decision from the tax question entirely.
One reservation covers a year of client gifts, and the program dashboard lists what has shipped, what is pending and what remains. That is what the annual gifting program is for: from 50 gifts a year (15% off from 100) you choose the box and your branding once, we hold the inventory in Costa Mesa, and each gift ships on its own to any contiguous-US address when the moment comes, shipping included, at the program rate of $89 per gift for Program Essential against $105 regular. Under 50 a year, a one-time order starts at 12 boxes; custom and logo-branded boxes start at 100.
Frequently Asked Questions
Q: Is the IRS $25 gift deduction limit per person or per gift?
A: The $25 limit applies per recipient, per tax year — not per individual gift occasion. If you send a client two separate gifts in one year totaling $80, your corporate gift tax deduction for that recipient is still $25 for the year, not $50.
Q: Do gift boxes with food or alcohol count as business gifts or meals?
A: It depends on whether the food or drink is consumed in your presence. A gift box of artisan snacks or wine sent to a client's office — with no expectation that you'll share it with them — is generally treated as a business gift subject to the $25 cap, not a meal expense. Meals have their own deduction rules (currently 50% deductible when business is discussed). When in doubt, ask your CPA which category a specific item falls into before you file.
Q: Can I deduct more than $25 per person if the gift is very high quality or personally meaningful?
A: No. The $25 cap under IRC Section 274(b) is a hard limit regardless of the gift's quality, thoughtfulness, or retail value — the IRS makes no exceptions for premium curation or personal significance. That said, only incidental costs that add no substantial value — engraving, gift wrap, postage — sit outside the cap; the box and its contents count toward the $25 figure. The smarter frame: spend what the relationship is worth, document it correctly, and treat the corporate gift tax deduction as a modest bonus rather than the justification for the budget.
Q: Does the IRS $25 gift deduction limit apply to employee holiday gifts?
A: No. The $25-per-recipient cap under IRC Section 274(b) limits the deduction for gifts to people outside the company — clients, referral partners, prospects. Gifts to employees fall under the compensation and fringe-benefit rules instead: a modest physical gift given occasionally can qualify as a de minimis fringe benefit and stay off the W-2, while cash and gift cards to employees are always taxable wages, with no small-amount exception. Gifts to employees that are compensation are deductible as compensation and are not squeezed by the $25 figure. The full treatment is in our guide to whether employee gifts are taxable; confirm the amounts and the classification with your CPA.
Ready to send? Tell us your head count and whether it's one address or many — get a quote on the Holiday Collection or build your own box. We reply within one business day. Christmas orders: Mon, Dec 14 for shipped boxes, Fri, Nov 20 if you want your logo on them.
Looking for corporate gifting? See Pacific Gift Box Co. →
Related: Corporate gifting guide
Request pricing
Tell us a little about what you need — we'll reply with ideas and pricing. Orders start at 12 boxes.